- HOME
- Investor Relations
- Management Policies
- Message from the CFO
September 2026
Review of the Fiscal Year Ended March 31, 2026, and Outlook for the Fiscal Year Ending March 31, 2027
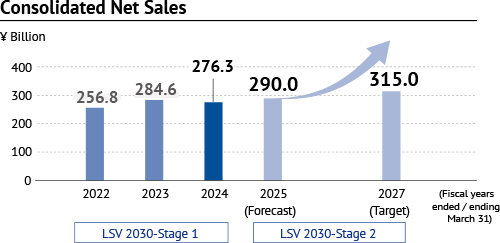
In the fiscal year under review (fiscal year ended March 31, 2026), we saw further record highs for net sales, operating income, and profit attributable to owners of parent. I believe that our ability to achieve such positive results in a highly uncertain business environment, which includes the significant disruption to various economies around the world brought about by U.S. tariff policy, is evidence of the steady improvement of our profitability. The driver of our performance has been Advanced Materials Operations, which develops semiconductor- and electronic component-related products. We recorded high levels of sales of the mainstay products in this business segment—semiconductor-related adhesive tape and equipment and multilayer ceramic capacitor-related tape—by solidly capturing the rise in demand related to AI. Despite a slight year-on-year decrease in sales of semiconductor-related equipment, there are signs of improvement, as we are seeing a steady recovery in both orders and deliveries for tools for high-bandwidth memory (HBM) manufacturing. This business segment is expected to maintain its strong performance in the current fiscal year (fiscal year ending March 31, 2027). Against a backdrop that includes the current status of the semiconductor market and strong capital investment by customers, all mainstay products are on track to achieve record-high sales.
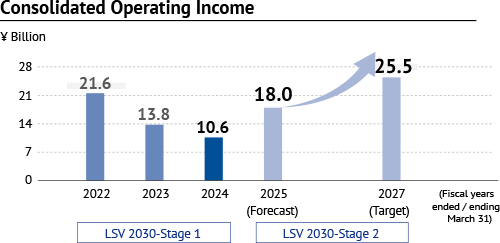
For the fiscal year ending March 31, 2027, we forecast higher net sales and income. We anticipate operating income to increase 9.3% year on year, to ¥27.5 billion. While we anticipate higher sales volumes to contribute ¥4.8 billion and price revisions to contribute ¥5.3 billion, rises in raw material prices will reduce income by ¥4.7 billion, and increases in fixed costs, such as labor and research and development expenses, will reduce income by ¥4.2 billion. Furthermore, in breaking down raw material prices, we must account for the impact of escalating tensions in the Middle East, which we estimate to be ¥3.0 billion. In fact, while raw material prices began to significantly rise in May 2026, our Procurement Division strove to secure raw materials before these price hikes, and we are making every effort to ensure a stable supply of products. In response to the impact of Middle East tensions, we implemented price revisions in Printing & Variable Information Products Operations on shipments from July 1, 2026. We also considered and are currently implementing price revisions in other business segments. Since these price revisions are not incorporated into our performance forecasts, we believe they will serve as a positive factor for our performance.
Improving MACTAC AMERICAS’ Profitability—A Key Challenge
Our strong financial performance clearly reveals a profit structure issue, as approximately 90% of our operating income comes from electronic and optical products, including Advanced Materials Operations, and the source of our income is heavily concentrated in a specific business division. In the fiscal year under review, operating income for Printing and Industrial Materials Products fell 63.8%, to ¥2.0 billion. However, the main factor behind this decline was the recording of an approximately ¥3.9 billion operating loss for MACTAC AMERICAS, LLC, our American subsidiary. In light of this situation, we must put considerable effort into driving improvements to profitability. As for the decline in process yield, the cause of the worsening operating loss, we have dispatched a team from Japan that includes engineers to address the issue. We anticipate seeing the effects of our improvements from around the second quarter of the current fiscal year. In addition, we implemented price revisions in April 2026 to cover soaring raw material costs, which are expected to result in several billion yen.
MACTAC AMERICAS will cease amortization of goodwill in November 2026. Since the burden of nearly ¥4.0 billion will be eliminated in the next fiscal year, we expect to remain in the black. However, as a business, we will aim to remain profitable. We aim to return to an operating profit margin of 10% as soon as possible, which was the rate we achieved prior to acquisition. Accordingly, we will expand our product lineup from the adhesive papers that have conventionally been our mainstay product to include adhesive films, which provide even more added value, as we strive to improve both unit price and profit margin. We will also implement measures to improve profitability while exploring ways to optimize our production and logistics sites.
Achievement of Crucial Targets Under Our Long-Term Vision
We estimate that our weighted average cost of capital (WACC) for the previous fiscal year was 6.1%. To consistently achieve a price-to-book value ratio (PBR) above 1.0, we recognize the importance of consistently maintaining a return on equity (ROE) that exceeds WACC. We have adopted an operating profit margin of 12% or more and ROE of 10% or more as a financial target for the final year of our mediumterm business plan, LSV 2030–Stage 3 (fiscal year ending March 31, 2030). LINTEC’s businesses are divided into three categories—growth areas, revenue base areas, and reconstruction areas. The key to achieving the above indicators is raising the profitability of our entire business portfolio. In addition to the aforementioned MACTAC AMERICAS, we also need to improve profitability in the reconstruction areas of Optical Products Operations and Fine & Specialty Paper Products Operations. Under the ongoing Stage 2 of the medium-term business plan, we closed two consolidated subsidiaries in South Korea and Taiwan that had been engaged in adhesive processing for polarizing films under Optical Products Operations. We have also seen a harsh external environment for Fine & Specialty Paper Products Operations with a shift from paper to digital media, which has lowered the sales volume for our core product, color papers for envelopes. Although not reflected in our financial results, Fine & Specialty Paper Products Operations plays a vital role in producing base paper for release paper and selling it internally to Converted Products Operations. This supports our integrated production system for adhesive products that is a LINTEC strength. With that said, improving profitability is still essential. In addition to recording impairment losses on fixed assets of ¥7.7 billion for the fiscal year ended March 31, 2025, we are implementing fundamental structural reforms, such as shutting down one of the paper machines operating at the Kumagaya Plant (Saitama Prefecture) to save on fixed costs.
In recent years, we have received numerous questions regarding optimization of our business portfolio at IR meetings, but we have not set uniform rules for investments and withdrawals. This is because we believe that, in a rapidly changing business environment, the ability to accurately assess each situation and make timely decisions allows for flexible responses aligned with individual circumstances. Accordingly, I view it as my important role to communicate clearly and sincerely with shareholders and investors, explaining the background behind our initiatives as well as LINTEC’s thinking and unique strengths.
Cash Allocation to Support Sustainable Growth
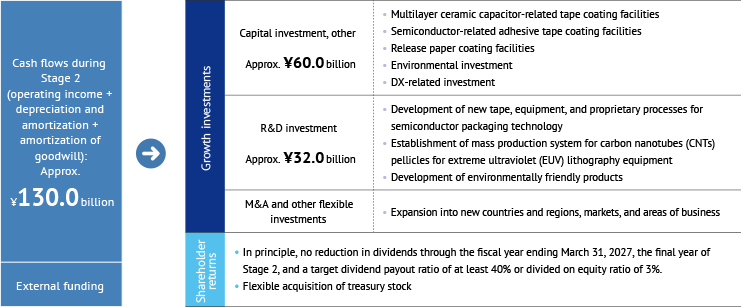
While we are advancing structural reforms in business operations that require improvements in profitability, we will enhance our competitive edge in Advanced Materials Operations, which is a growth area, by actively investing funds in R&D and capital expenditures. In the fiscal year under review, we actively pursued growth investments in our semiconductor-related businesses, investing a total of ¥3.0 billion in establishing a mass production system for carbon nanotube (CNT) pellicles for extreme ultraviolet (EUV) lithography equipment, expanding and renovating the Ina Technology Center (Saitama Prefecture) to strengthen supply capacity for semiconductor-related equipment, and constructing new research facilities for developing new products such as semiconductorrelated adhesive tape. In the current fiscal year, we will continue projects carried over from the previous period, as well as advance new initiatives such as building new systems related to advanced semiconductor manufacturing processes. Regarding our forecast of only a 2.6% year-on-year increase in operating income for electronic and optical products for the current fiscal year, we have received numerous questions from investors asking whether this forecast is overly conservative relative to the growth of the global semiconductor market. This forecast reflects increased fixed costs and rising raw material prices due to escalating tensions in the Middle East. However, given that actual results in the fiscal year under review significantly exceeded initial forecasts, I believe there is considerable potential for performance to exceed the current projection. Proactive investment in growth areas such as Advanced Materials Operations is central to our Companywide strategy. Currently, our Companywide R&D expenditure to sales ratio is approximately 4%, and we are considering raising this to around 10% in the future. We will disclose our cash allocation plans for the next medium-term business plan period at an appropriate time.
In addition, as part of our efforts to refine management, we will continue managing our businesses using return on invested capital (ROIC). Asset turnover rates are trending favorably, reflecting steady progress toward management practices that emphasize capital efficiency. In the current fiscal year, we have established KPIs such as inventory turnover, trade receivables turnover, and fixed asset turnover, promoting improvement activities across each business operation. We also introduced a new ROIC management accounting system in April 2026. We have strengthened our framework by inputting quarterly performance data for each business operation, enabling data-driven progress management and decision-making. We believe this will further advance improvements in profitability and capital efficiency across each business operation.
Constructive Dialogue with Shareholders and Investors
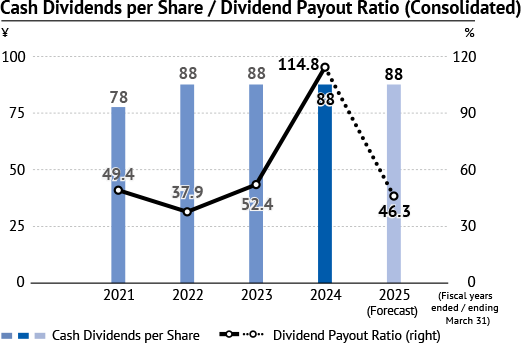
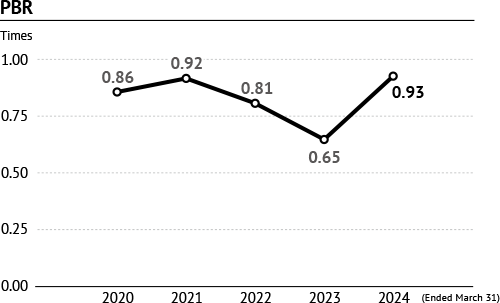
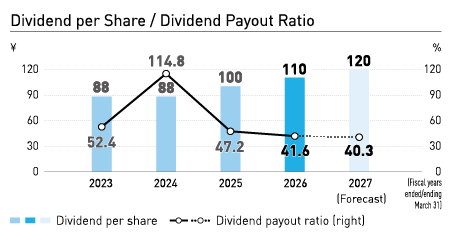
During IR meetings with investors, we receive questions regarding the optimization of our business portfolio. We also receive requests for strengthening shareholder returns, such as the aforementioned clarification of cash allocation, promotion of ROIC management, and ongoing share buybacks and dividend increases. Regarding share buybacks, we repurchased 3 million shares (approximately ¥8.3 billion) in June 2025. Going forward, we will continue to implement flexible share buybacks as appropriate, taking into account cash on hand and assessing the necessity of such actions. Our basic policy through the fiscal year ending March 31, 2027 is to avoid dividend reductions, in principle, and maintain a dividend payout ratio of 40% or higher or a dividend on equity (DOE) ratio of 3% as a benchmark. For the current fiscal year, we plan to increase the dividend by an additional ¥10, to ¥120, marking the third consecutive year of dividend increases.
Despite a significant fall in our stock price due to the shock caused by President Trump’s tariffs in April 2025, we have since seen a strong resurgence in performance and our stock price has consistently maintained a PBR above 1. I believe this reflects strong market interest in our competitive semiconductor-related businesses, as well as positive recognition from investors for our ability to swiftly implement structural reforms in response to their expectations. At present, we continue our dialogue with the market through ongoing communication with institutional investors both in Japan and overseas, as well as continued participation in corporate presentations for individual investors. We will continue to strive for further improved corporate value and acquisition of market recognition through active information disclosure and constructive dialogue.